Without intent, your budget is just wishful thinking. Budgeting with intent means assigning every dollar a clear purpose—whether it’s paying down debt, building an emergency fund, or investing for your future. Instead of hoping your financial situation improves by chance, you're proactively directing your money exactly where it needs to go.
Picture Mark, who used to wonder why he never had money left at the end of the month. He'd spend impulsively and feel stressed when bills came due. Once Mark began budgeting intentionally, clearly defining his spending and savings targets, his financial anxiety disappeared. Suddenly, every paycheck had a purpose, and Mark felt confident about his financial future.
Estate planning might sound like a big, scary term, but it's really just about making sure the things you own and care about go to the right people when you're no longer around. Let's break it down in simple terms, so you can understand how to protect your legacy.
1. Define Your Financial Destination

If you don’t know where you're going, any road will get you there—and financially, that road often leads nowhere. Clearly defining your financial goals creates a roadmap for your money. Break these goals down into short-term (paying off a credit card, saving for a vacation), mid-term (buying a home, funding education), and long-term (retirement, financial independence).
Make each goal specific by adding a target amount and deadline. For example, if you want to save $2,400 for a planned expense in 12 months, your budget needs to reserve $200 each month. If that amount does not fit, adjust the deadline, reduce the target, or free money from another category. For retirement goals, review your plan's rules, fees, and available benefits using the U.S. Department of Labor retirement plan guidance and its guide to retirement plan fees and expenses.
Here’s how to simplify your financial roadmap
Identify and define your goals
- Short-term: Quick wins and immediate needs
- Mid-term: Big life purchases and milestones
- Long-term: Lifelong financial security and independence
Prioritize your goals
- Rank goals by urgency and personal importance
- Tackle high-priority goals first.
Align your actions
- Set clear spending, saving, and investing habits tied to each goal
- Regularly track progress to stay motivated
Review and adapt your plan
- Adjust goals as your life and circumstances change
- Celebrate progress and recalibrate regularly
When your financial path is defined, every dollar gains purpose, momentum builds, and reaching your dreams becomes predictable rather than wishful thinking. Treat contributions toward those priorities as planned expenses rather than whatever is left over, following Law 2: Pay Yourself First.
2. Know Exactly Where Your Money Is Going

Ignorance isn't bliss; it's bankruptcy. Too many people avoid looking closely at their expenses because they're afraid of what they'll find. But ignoring reality doesn’t change it—it only makes things worse. The path to financial control starts with knowing precisely how your money flows in and out every month.
Start today by tracking every penny spent. Use a budgeting app, spreadsheet, or even a notebook—whatever works best for you. Challenge yourself to track expenses for the next 30 days. You'll quickly identify wasteful spending and discover opportunities to redirect money towards your real priorities.
Review checking accounts, credit cards, digital wallets, and automatic payments so nothing is missed. Mark recurring expenses separately and check whether each one is monthly, quarterly, or annual. A $120 annual subscription may not appear in an ordinary month, but it still requires $10 of monthly planning. Also compare what you planned to spend with what actually cleared your accounts; the difference shows where your assumptions need work.
If you're serious about taking control of your finances, Rocket Money is a game changer. It effortlessly tracks your spending, identifies hidden subscriptions, and clearly highlights where your money goes each month. With easy-to-read insights and automated budget tracking, Rocket Money turns the tedious task of expense tracking into a simple, stress-free habit. Give yourself clarity, save money, and finally see exactly where every dollar is headed.
- Stop Failing to Follow a Budget. Keep it Simple — Master the 50/30/20 budgeting strategy using Rocket Money, an app that tracks income, expenses, and sets clear goals. Automate your expense monitoring
At the end of the 30 days, choose one recurring charge to cancel, reduce, or replace and assign that exact amount to a goal. If rising spending has become your new normal, review how small lifestyle upgrades can slow wealth building.
3. Create a Zero-Based Budget

If every dollar doesn't have a job, it'll find one—and usually not a productive one. Zero-based budgeting means allocating your entire monthly income to specific categories, including necessities, savings, debt payments, investments, and even fun. The goal is simple: income minus expenses equals zero.
Imagine earning $5,000 per month. With zero-based budgeting, you might allocate $2,500 to essentials, $1,000 to savings and investments, $1,000 to debt payments, and $500 for entertainment. By intentionally assigning roles to every dollar, you eliminate impulsive spending, reduce financial anxiety, and supercharge your progress toward your financial goals. When deciding how much to direct toward credit card debt, account for how the issuer calculates interest using the Consumer Financial Protection Bureau’s credit card interest guidance.
A zero-based budget does not mean spending your bank balance down to zero. It means every dollar of expected income has been assigned, including money kept in savings or reserved for upcoming bills. If the assignments total only $4,700 in the example above, the remaining $300 still needs a job. You could send it to an emergency fund, add it to a debt payment, or reserve it for a known expense. If you do not yet have a cash reserve, use Law 5: Build an Emergency Fund to make that category an intentional priority.
Include sinking funds for costs that are predictable but do not arrive every month, such as car repairs, insurance premiums, gifts, or school expenses. If you expect a $600 bill in six months, setting aside $100 per month prevents that bill from disrupting the rest of your plan. The guide to planning for predictable expenses explains why overlooking these costs can lead to avoidable debt.
Income timing matters too. Someone paid twice monthly may have enough income overall but still face a cash shortage before a bill is due. Match each bill to a paycheck, keep a small checking buffer, and save ahead for major purchases when practical. The Consumer Financial Protection Bureau guidance for preparing for a major purchase can help you consider the preparation involved.
Before the month begins, confirm that every category—including savings and irregular expenses—adds up to your expected take-home income.
4. Prioritize Needs, Wants, and Goals
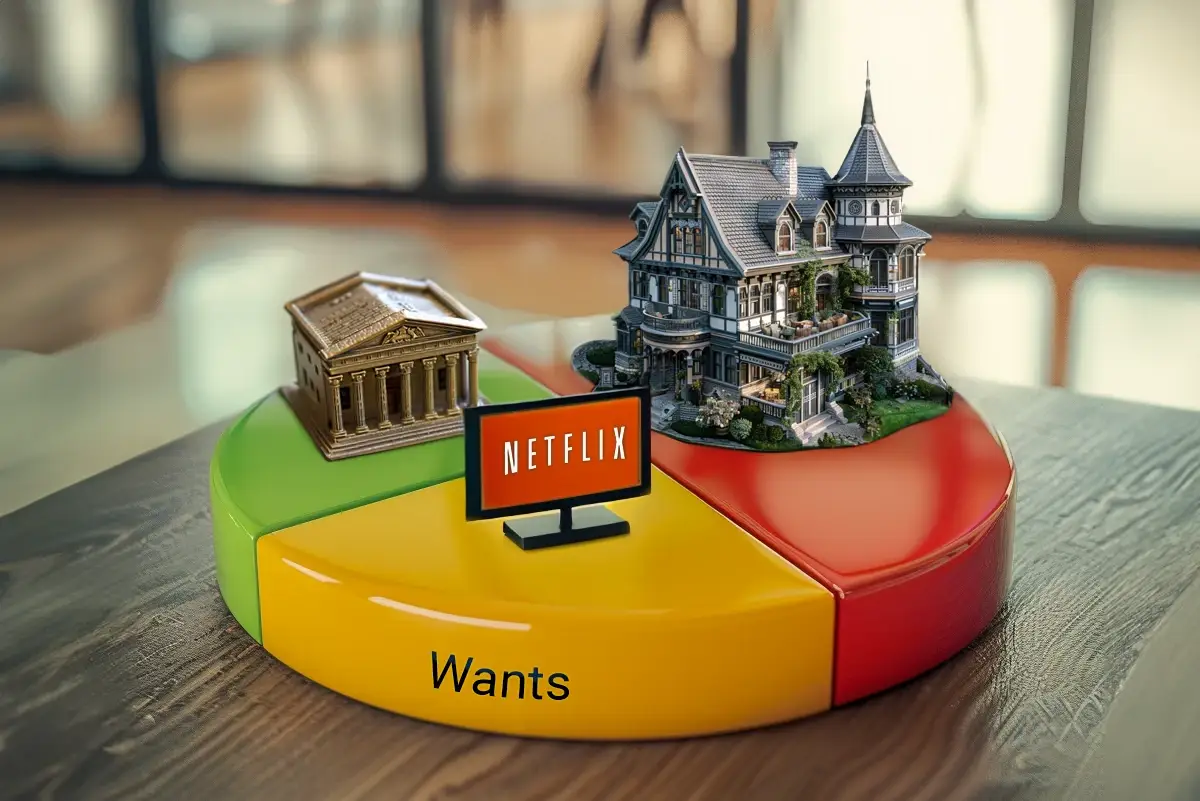
Budgeting is like meal prepping—prioritize protein (needs), enjoy dessert in moderation (wants), and always pack snacks for later (goals). Clearly distinguish between essential expenses (housing, groceries, utilities), comforts (eating out, streaming services, shopping), and future-focused financial priorities (savings, debt reduction, investing).
Take last month's bank statement and categorize each expense into these three buckets. Be brutally honest. You might realize you're overspending on "desserts" and not packing enough "snacks" for later. By consciously shifting money from wants to goals, you'll build momentum toward your ideal financial future.
The categories depend on context. Internet access may be a need for remote work, while a faster premium plan may partly be a want. A car payment may be necessary where public transportation is unavailable, but the vehicle upgrade within that payment may not be. When an expense serves both purposes, classify the essential portion as a need and the upgrade as a want.
Challenge borderline expenses by asking what would happen if you reduced or removed each one. Then choose one want you can reduce without making the budget so restrictive that you abandon it, and redirect the difference to your highest-priority goal.
5. Automate Your Intentions With Law 6

Automation beats motivation every single time—and Law 6 proves it. Law 6 emphasizes creating systems that run smoothly without constant oversight, ensuring your financial decisions are consistent and effective, regardless of your day-to-day emotions or motivation levels.
Apply this by automating your savings, investments, and debt repayments. Tools like Ally Bank, Wealthfront, or Rocket Money streamline the process, making intentional budgeting effortless. By leveraging automation, you turn your good financial intentions into reliable habits, moving steadily toward your goals, day after day.
Schedule transfers shortly after income arrives, but leave enough money in checking for bills and normal fluctuations. If your income varies, automate a conservative base amount and make a manual supplement during higher-income months. Review the system after a pay change or major bill rather than assuming an old transfer still fits.
Law 6: Automate Your Finances explains how to set up systems that manage your money automatically. Choose one transfer or payment to automate this week, then verify the first transaction before relying on it.
6. Avoid Common Budgeting Pitfalls

Even the best budgets can derail if you’re not careful. Watch out for these traps:
- Too Restrictive: Extreme frugality often backfires. Allow some flexibility for fun to avoid burnout.
- Budget Denial: Ignoring reality won't solve financial issues. Face your finances head-on.
- Neglecting Small Expenses: Coffee runs or subscriptions might seem minor, but they add up fast.
- Forgetting Irregular Costs: Build monthly sinking funds for expenses that arrive quarterly, annually, or unpredictably.
- Using Idealized Numbers: Base the first draft on recent statements rather than what you think groceries, transportation, or entertainment should cost.
- Ignoring Cash-Flow Timing: Assign bills to specific paychecks so a sound monthly plan does not create a midmonth shortage.
The solution? Stay balanced, honest, and vigilant. Address small issues before they become big problems, and periodically refresh your motivation by reminding yourself of your financial "why." Set a 15-minute monthly review to compare planned and actual spending, refill irregular-expense categories, and adjust the next month's assignments.
Put Your Intentional Budget Into Action
Budgeting with intent isn't about restriction—it's about empowerment. When you control your money, you control your future. Commit today to giving every dollar a purpose, aligning your spending with your deepest values and most exciting goals.
- Write down your three highest-priority financial goals with amounts and deadlines.
- Track every expense for 30 days and identify one recurring cost to change.
- Assign all expected monthly income across needs, wants, goals, and irregular expenses.
- Automate one priority payment or savings transfer and verify that it clears safely.
- Review the plan monthly and revise the numbers when your income, bills, or goals change.
Start budgeting intentionally now by giving the next dollar you earn a specific job.