In the unpredictable world of finance, having an emergency fund is your first line of defense against life's unforeseen challenges. This safety net not only protects you from financial turmoil but also safeguards your hard-earned net worth. Discover why an emergency fund is crucial and how to build one effectively.
Why You Need an Emergency Fund
An emergency fund is crucial because it acts as a financial buffer in times of unexpected expenses, such as medical emergencies, car repairs, or sudden job loss. Without it, you might find yourself relying on credit cards or loans, which can quickly spiral into debt.
How Much Should You Save?

The general rule of thumb is to save enough to cover 3 to 6 months of living expenses. This range provides a comfortable cushion for most people, but your specific needs might vary based on job stability, dependents, and lifestyle.
Calculate Your Expenses
To determine how much to save, start by calculating your monthly expenses. Include essential costs such as rent, utilities, groceries, and transportation. Multiply this number by the number of months you wish to cover. Don't forget nonmonthly costs like annual premiums, since irregular bills that quietly become debt catch many people off guard.
For example, if your essential expenses are $3,200 a month and you want six months of coverage, your goal is $3,200 × 6 = $19,200.
Where to Keep Your Emergency Fund
Accessibility is key when it comes to emergency funds. Consider keeping the money in a high-yield savings account where it can earn interest but remains liquid enough for immediate use. If you want your cash to work harder while it sits, compare that with an interest-earning checking account.
Automate Your Savings
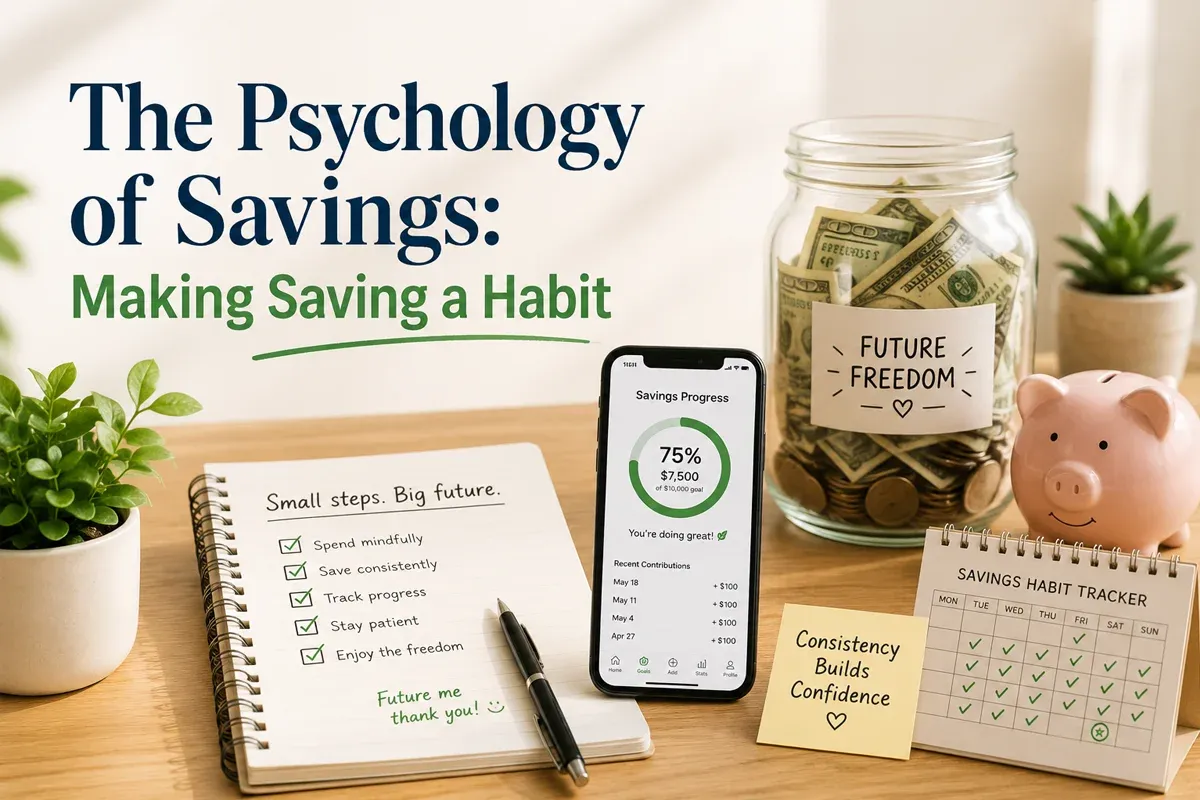
Set up automatic transfers from your checking account to your savings account. This ensures consistency and removes the temptation to spend the money elsewhere.
Building It Over Time
Don't be discouraged if you can't fully fund your emergency savings right away. Start small, and incrementally increase your savings rate as your financial situation improves. Consistency is more critical than speed.
Replenishing Your Emergency Fund
After dipping into your emergency fund, make it a priority to replenish it as soon as possible. Reassess your savings goals and adjust if necessary to ensure you're prepared for future emergencies.
Regularly Review Your Fund
Financial situations change, and so should your emergency fund. Review your fund annually to ensure it meets your current needs and adjust your savings plan accordingly.
The Peace of Mind Benefit
Beyond financial stability, an emergency fund provides peace of mind. Knowing you have a financial buffer reduces stress and allows you to focus on long-term financial goals without the constant worry of unexpected setbacks.
Incorporate building an emergency fund into your daily financial habits. Not only does it protect your net worth, but it also sets a strong foundation for overall financial health.